The Psychology of the GTA Housing Market: Dismantling 'Fear vs. Logic' in 2026
By Nik Thakkar - Real Estate Broker & Investment Strategist
Published: March 4, 2026 | Estimated Reading Time: 12 Minutes
It’s no secret that the Greater Toronto Area real estate market is powered as much by emotion as it is by interest rates. In 2026, the dominant emotion is undeniable: Fear.
Buyers are afraid of high carrying costs. Sellers are afraid they missed the peak. Everyone is afraid of making the 'wrong' move in an unpredictable economy. This collective anxiety often creates a paralytic state where potential buyers sit on the sidelines, waiting for a hypothetical perfect moment that may never arrive. My philosophy is simple: **Fear stops wealth generation. Logic starts it.**
The Anatomy of Real Estate Fear: What Drives the Anxiety?
Fear thrives on generalized headlines. When you see news reports stating "GTA Home Sales Down 25%," the fear centers in your brain interpret that as a total market crash. But a blanket statement about the GTA does not apply to a specific townhouse complex in Milton or a new build development in Vaughan.
In 2026, the primary fears driving inactivity are:
- The Rate Trap: "Interest rates are stabilized at 4%, but if they rise again, I'll be underwater."
- The Credit Crisis: "My credit score isn't perfect; I can't qualify for a good mortgage."
- The Value Anxiety: "Prices have fallen slightly from 2022; what if they never go back up?"
Dismantling Fear with Logic: The Nik Thakkar Approach
To make a logical decision, you must strip away the noise and look at the actual data for the hyperlocal markets I serve: Milton, Mississauga, Oakville, Guelph, Brampton, Burlington and Hamilton. The 2026 market isn't a single story; it is a tale of highly segmented opportunities.
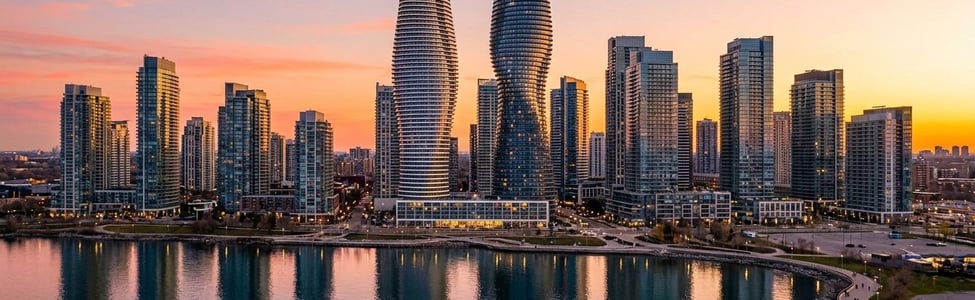
(The Mississauga skyline represents a mature market with abundant opportunity for entry-level condo buyers in 2026.)
The Core Logic Principle: Total Cost of Ownership vs. Rent
If you are waiting for rates to drop further, you must calculate the cost of that wait. In many GTA markets, rental costs have kept pace with inflation. When you rent a home for $3,500/month, you are effectively paying 100% interest to your landlord. Every single month you wait on the sidelines, you are losing equity and paying down someone else's mortgage.
The "Landlord Tax" Calculation
When you pay $3,500 in rent, your return on investment is exactly 0%. Here is how that compares to a mortgage at 2026 rates:
| Component | Renting ($3,500/mo) | Owning ($4,200/mo) |
|---|---|---|
| Interest / Waste | $3,500 (100%) | ~$2,800 (Interest + Taxes) |
| Equity / Savings | $0 | +$1,400 (Avg. Principal) |
| True Monthly Cost | $3,500 | $2,800 |
The Logic: Even with a higher monthly "sticker price," owning a home in the GTA is actually $700/month cheaper because you aren't throwing 100% of your money into your landlord's equity.
Deep-Dive Analysis: Fear vs. Logic Across 3 Key Personas
To prove how logic dismantles fear, let’s run the numbers for three real-world scenarios in the current March 2026 landscape.
1. The First-Time Buyer with Imperfect Credit
The Fear: "My credit score is 630. I'll get rejected by A-Lenders or forced into a predatory rate."
The Logic: The Strategic B-Lender Bridge. In 2026, a 630 score is common. Instead of waiting years to fix it, we leverage a 2-year strategic bridge with a reputable B-Lender.
| Scenario (Purchase: $750k Condo) | Logic: Buy Now (B-Lender) | Fear: Wait 2 Years (Rent) |
|---|---|---|
| Down Payment | $75,000 (10%) | $75,000 + Lost Rent |
| Interest Rate | 5.5% (Bridge) | 4.0% (Future A-Rate) |
| Monthly Carry | ~$4,100 | ~$3,550 |
| The 2-Year Win | +$50,000 (Equity + Appr.) | -$84,000 (Rent Paid) |
2. The Move-Up Family (Condo to Detached Home)
The Fear: "I’m losing $50,000 by selling my condo below its 2022 peak!"
The Logic: The 'Equity Gap' Strategy. Focus on the Gap, not just the sale price. Buying the upgrade now is cheaper than it was at the peak.
| Market Timing | Condo Sale Value | Detached Purchase | The "Gap" Cost |
|---|---|---|---|
| 2022 Peak | $750,000 | $1,350,000 | $600,000 |
| 2026 Reality | $700,000 | $1,150,000 | $450,000 |
| Net Difference | -$50,000 | -$200,000 | +$150,000 Advantage |
3. The 'Cash Flow' Investor (Positive vs. Negative)
The Fear: "With 20% down, single-family homes are cash-flow negative in Milton."
The Logic: The Secondary Suite Multiplier. Maximize revenue from the same footprint by adding a legal secondary suite.
| Metric ($850k Home) | Fear: Standard Rental | Logic: Dual-Suite Strategy |
|---|---|---|
| Monthly Expenses | $3,900 | $4,100 (Inc. Suite Costs) |
| Upper Unit Rent | $3,200 | $3,200 |
| Lower Unit Rent | $0 | $1,800 |
| Net Cash Flow | -$700 (Negative) | +$900 (Positive) |
Conclusion: It’s Time to Re-Write Your GTA Narrative
The GTA real estate market in 2026 is a landscape of complex, highly rewarding opportunities for those willing to do the math. When you replace generalized fear with localized, specific data, the smart move becomes clear.
Ready to apply Logic to your next Real Estate move?
I will generate a custom 'Fear vs. Logic' ROI report specifically for your budget and target neighborhood in the GTA.
Request Your Logic ReportOr Call Nik Now: 289-644-9988