The 2026 Move-Up Pivot: Why Halton Freeholds are the Velocity Leaders
If you’ve been sitting in a GTA condo watching the market, March 2026 has presented a unique "Goldilocks" window. Interest rates have hit a steady floor, and the inventory gap between condos and townhomes is narrowing.
1. The Velocity Gap: Freeholds vs. Apartments
Recent March 2026 data for Oakville and Milton shows a diverging story. While the apartment sector is seeing a slight price softening (-0.8% HPI), Freehold Townhomes have seen absorption rates soar from 15% to nearly 22% in just 30 days.
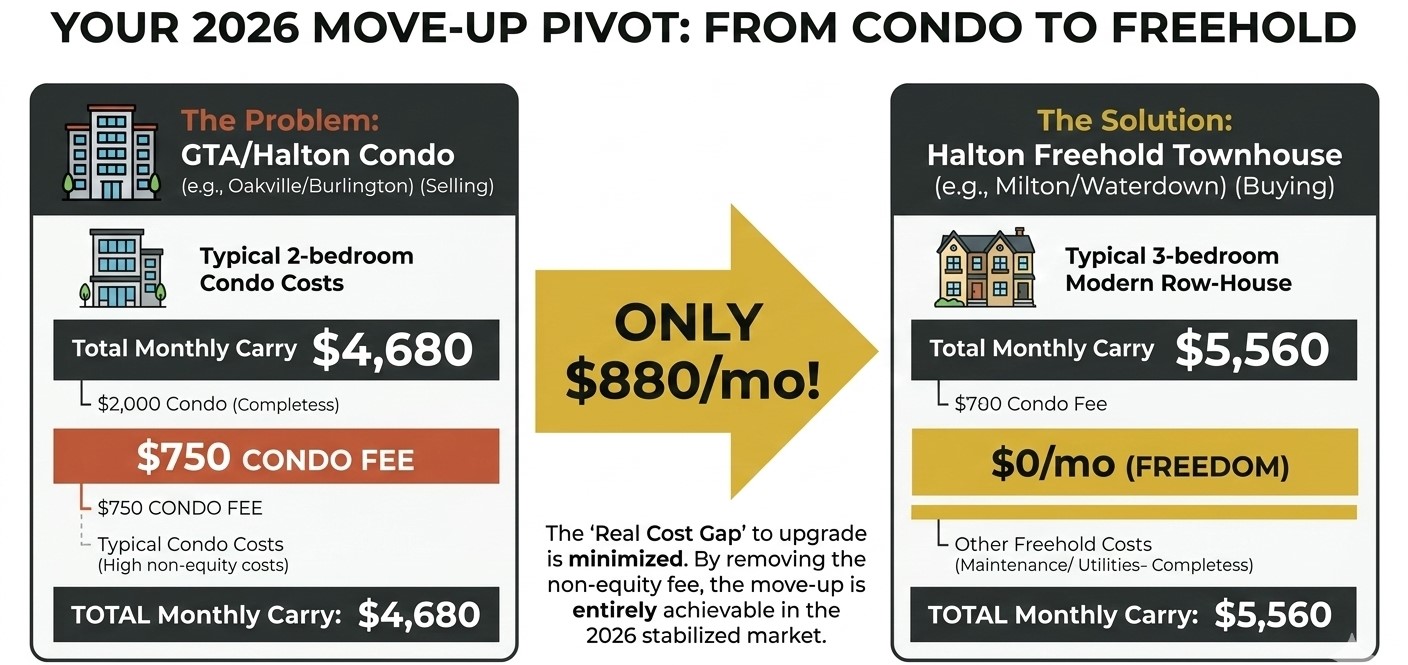
The 2026 Math: By removing the $750/mo non-equity fee, the upgrade to a freehold is only an $880/mo pivot.
Boots on the Ground: March 2026 Stats
- Freehold Townhomes: 21.8% Absorption (Sellers' edge returning).
- Condo Apartments: 13.3% Absorption (Pure Buyers' market).
- Detached (Mid-Market): 27 Days on Market (Fastest moving segment).
2. The "Condo-to-Freehold" Math
The price spread in Milton and Oakville has become much more manageable. When you eliminate the average condo fee of $750/mo, your "Move-Up Power" increases significantly.
| Property Type | Avg. Price (Halton Region) | Monthly Carry (at 3.75% Fixed) |
|---|---|---|
| Standard 2-Bed Condo | $656,000 | $3,030 + High Condo Fees |
| 3-Bed Freehold Town | $996,000 | $4,600 (Zero Condo Fees) |
3. Two 2026 Rules That Changed the Game
Two major federal policy shifts are fueling this move-up wave in the Halton and Peel regions:
- The $1.5M Insured Cap: You can now purchase a home up to $1.5M with less than 20% down. This has unlocked the "Executive Townhome" market in Oakville for families who have equity but don't want to liquidate their entire portfolio for a $300k down payment.
- Universal 30-Year Amortization: This is now available on all homes for move-up buyers. It effectively increases your "Trade-Up Power" by roughly 10% compared to 2024 standards, allowing for much lower monthly obligations.
4. 2026 Mortgage Rate Calculus
With the Bank of Canada holding steady at 2.25% this March, choosing the right product is about risk tolerance versus immediate cash flow.
| Rate Product | March 2026 Avg. | 30-Year Impact |
|---|---|---|
| 5-Year Fixed | 3.75% | Maximum Stability; Increases Power by 10% |
| 3-Year Fixed | 3.99% | Balance of rate and future flexibility |
| Variable (Adjustable) | BoC + 0.5% (~4.25%) | Maximum flexibility for early renewals |
Ready to Execute Your Move-Up Pivot?
I specialize in "Concurrent Trades"—selling your condo while securing your freehold without the stress of owning two mortgages.