How to Buy a Milton Home in 2026: Bad Credit & Tax Hike Survival Guide. The 2026 Reality Check for Milton Buyers
By Nik Thakkar - Real Estate Broker & Investment Strategist
Published: January 2026 | Estimated Reading Time: 12 Minutes
Introduction: The 2026 Reality Check for Milton Buyers
As we enter January 2026, the Milton real estate market presents a complex paradox for prospective buyers. On one hand, interest rates have finally stabilized after the volatility of the early 2020s, bringing some predictability back to mortgage payments. On the other hand, a new set of financial hurdles has emerged right here at home. With the Town of Milton and Halton Region finalizing a significant 4.75% blended property tax increase for 2026, the cost of carrying a home has just gone up.
For a first time home buyer in Milton—especially one grappling with bruised credit—the dream of homeownership can feel like it's slipping further away. The traditional path of walking into a big bank with a 650 credit score and getting an easy approval is largely gone.
The 2026 Strategy
But 2026 is not the year to give up; it’s the year to get strategic. This guide is designed for the buyers the big banks ignore. We are going to move beyond generic advice and dive into the "Milton Mortgage Hack." We will show you how to leverage specific local zoning bylaws to turn a "tax problem" into an "income solution," negotiate hard on "stale listings," and navigate the alternative lending landscape to secure your future in one of Canada’s fastest-growing communities.
1. The B-Lender Pivot: Buying with Bad Credit in Ontario
If your credit score is below 640 due to past consumer proposals, missed payments, or high utilization, traditional "A-Lenders" (the Big Five banks) will likely decline your mortgage application in 2026. They are strictly regulated and rely heavily on automated scoring.
However, this is not the end of the road. The solution for thousands of buyers seeking bad credit home loans in Ontario is the "B-Lender" market.
Understanding the B-Lender Landscape
B-Lenders (like Home Trust or Equitable Bank) are legitimate financial institutions that cater to clients who don't fit the perfect "A-box." They focus less on your past credit score and more on two things:
- The Equity: They need to know the property is worth the investment.
- Your Ability to Repay: They look at your current income versus debts, rather than just a three-digit score.
The trade-off? B-Lender rates in 2026 are typically 1% to 2% higher than bank rates, and they almost always require a minimum 20% down payment. They generally do not deal with insured mortgages (less than 20% down).
Unique Insight: The "Credit Staging" Strategy
Smart buyers in 2026 aren't viewing a B-Lender mortgage as a 25-year commitment. They view it as a 2-year bridge. We call this "Credit Staging."
By securing a B-Lender mortgage now, you get into the Milton housing market and start building equity. You use that 2-year term to make every mortgage payment on time, which aggressively repairs your credit score. Once your score crosses the 680–700 threshold, your Milton mortgage broker for bad credit can refinance you back to an "A-Lender" at a lower rate. It’s a short-term cost for long-term gain.
2. The 2026 Regional Comparison: Taxes, Prices, and the "Carry Cost"
Milton has historically been the "value alternative" to Oakville and Burlington. However, the Milton property tax 2026 hike has many buyers questioning if that's still true. To make the right decision, you need to look at the total monthly "carry cost," not just the tax rate.
While Oakville boasts a lower municipal tax rate increase (1.96% for the town portion in 2026), the entry price for a detached home there is significantly higher. Milton remains the strategic choice for buyer's needing income "helpers" because its bylaws are more favorable for secondary suites.
The 2026 Carry Cost Comparison Table
| Metric | Milton | Oakville | Mississauga |
|---|---|---|---|
| Mortgage | $4,796 | $4,796 | $4,796 |
| Property Tax | $721 | $608 | $812 |
| Gross Monthly Cost | $5,517 | $5,404 | $5,608 |
| Rental Income | ($2,200) | $0 | ($1,850) |
| Net Cost | $3,317 | $5,404 | $3,758 |
A detailed data table comparing the monthly costs of owning a home in Milton versus Oakville and Mississauga. It highlights that despite Milton's higher 2026 tax hike, the ability to easily add a legal basement suite ($2,200 income) makes the "Net Out-of-Pocket Cost" over $2,000 cheaper per month than Oakville.
3. The "Mortgage Hack": 2026 Legal Basement Requirements
For buyers with high debt ratios or bad credit, the legal basement in Milton, Ontario is not just a nice-to-have bonus; it is essential for mortgage qualification.
In 2026, lenders (especially B-Lenders) will allow you to add 50% to 80% of the projected rental income from a legal suite to your personal income application. This can turn a "Declined" application into an "Approved."
Navigating the 2026 Building Code & Local Bylaws
You cannot just throw a mattress in a basement and call it legal. To qualify for the income boost, the unit must be compliant.
Major Ontario Building Code Changes (Effective March 31, 2026):
- Radon Mitigation: All newly constructed secondary suites now require active soil depressurization systems to vent radon gas.
- HVAC Requirements: The heating system must be capable of maintaining 18°C throughout the suite, which often requires upgrading the furnace or adding supplemental heating.
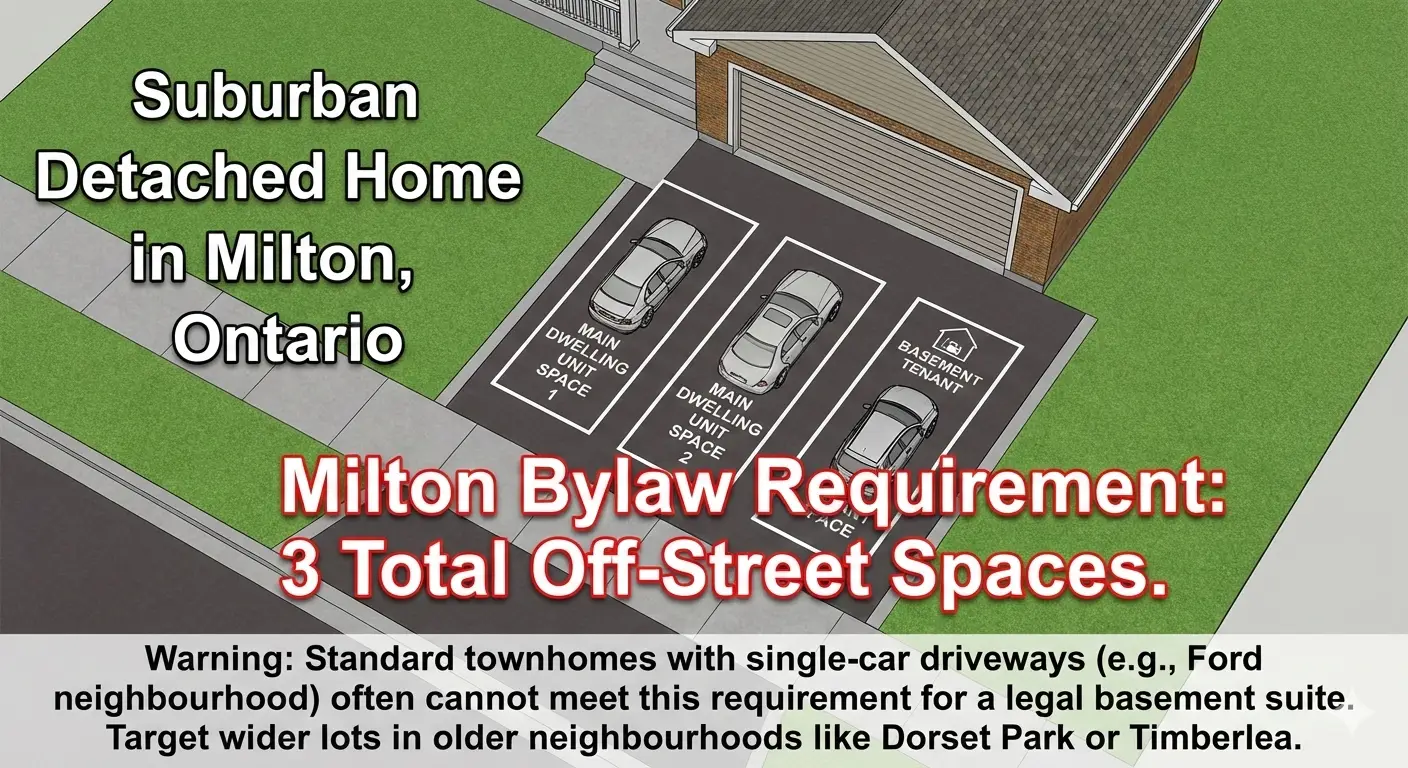
Milton’s "3-Parking Rule" Warning
If you buy a townhouse with a single-car driveway in the Ford neighbourhood, you likely cannot legally build a basement suite because you cannot provide the third parking spot. You must target specific property types, often found in older neighbourhoods like Dorset Park or Timberlea, that have wider lots.
4. Your Secret Weapon: Finding "Stale Listings"
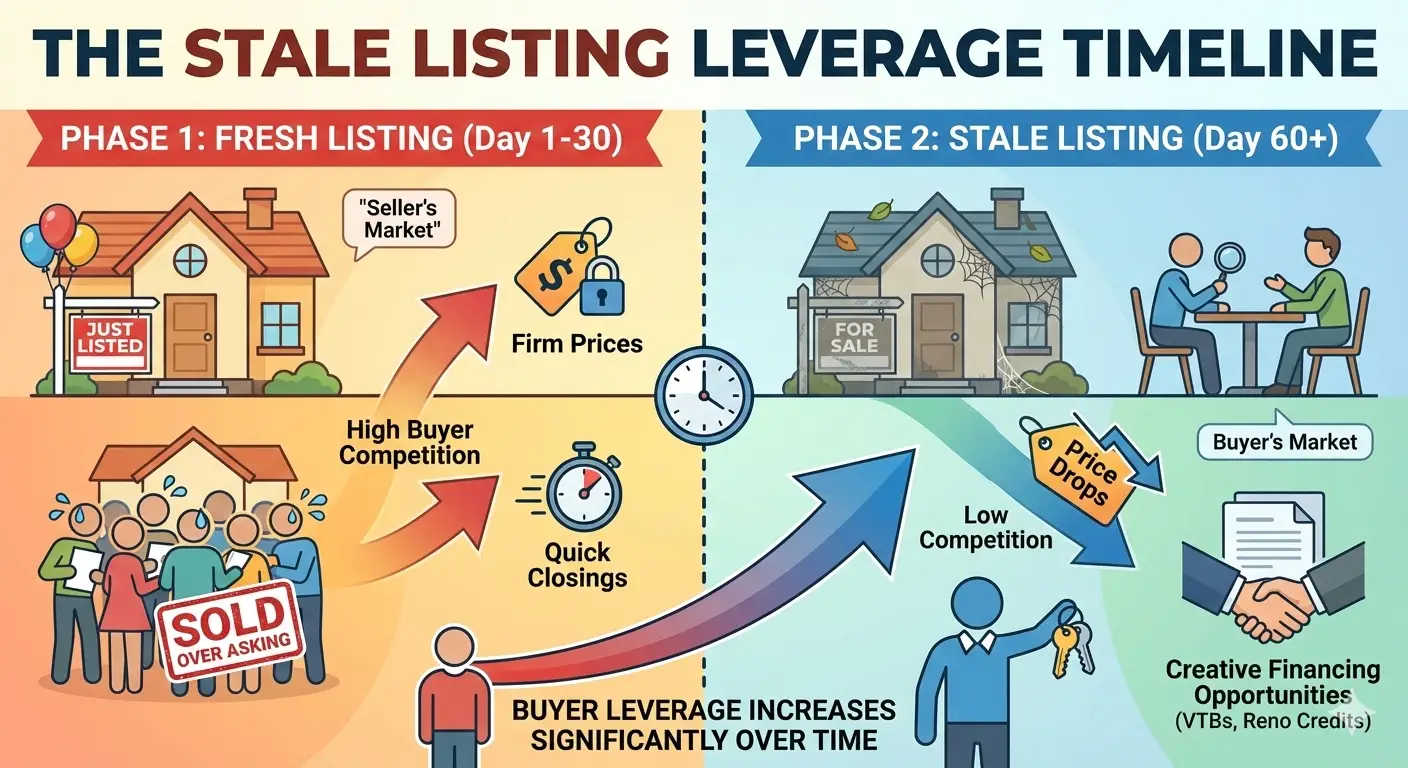
We mentioned earlier that B-Lenders require a 20% down payment. If you only have 10% saved, how do you bridge the gap? You target stale real estate listings.
In January 2026, the average home in Milton sells in about 34 days. Any listing sitting on the market for 60 days or more is considered "stale." These sellers are often frustrated, weary of low-ball offers, and highly motivated.
The Strategy for Bad Credit Buyers
- Negotiate the Price Down: Use the 2026 tax hike and required radon upgrades as justification to hammer the price down, effectively lowering the 20% down payment amount you need.
- Vendor Take-Back Mortgage (VTB): In some cases, you can ask the seller to become the lender for a portion of the down payment.
- Flexible Closing: B-Lender mortgages are complex and take time. A seller of a stale listing is more likely to agree to a 90-day closing.
The 2026 "Grant Stack": Free Money for Milton Buyers
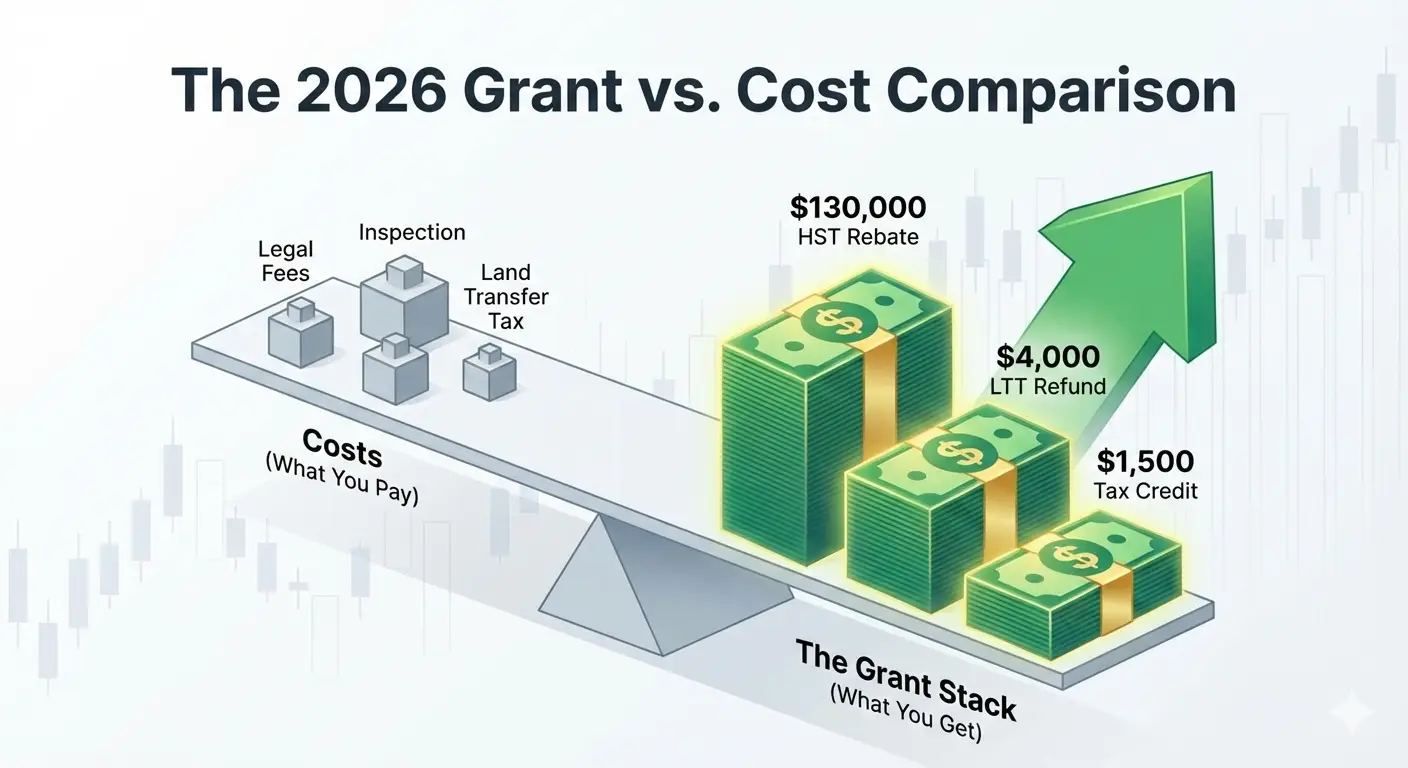
When searching for a first time buyer grant, many residents are surprised to find that the total incentives available in 2026 can exceed $140,000. Here is the breakdown:
| Grant Component | Value | Strategy |
|---|---|---|
| HST "Super Rebate" | Up to $130,000 | New builds or "Substantial Renovations." |
| Land Transfer Tax Refund | $4,000 | Immediate credit at closing for resale homes. |
| Home Buyers’ Tax Credit | $1,500 | Non-refundable credit to offset legal fees. |
The "Grant Grab" Checklist:
- Buying a new build? (Claim $130,000 HST)
- Buying resale? (Claim $4,000 LTT Refund)
- Using an RRSP? (Claim $60,000 HBP “Self-Loan”)
- Building a suite? (Claim $80,000 Suite Loan)
Quick Takeaways
- The 2026 Tax Reality: Milton's blended property tax has increased by approx. 4.75%.
- Bad Credit Solution: Use B-Lenders as a 2-year bridge and focus on rebuilding credit.
- The Offset Hack: A legal basement suite can significantly lower net monthly costs.
- The Parking Trap: Ensure the property allows three legal parking spaces.
- Target Stale Listings: Homes listed 60+ days offer better negotiation opportunities.
Next Step in Your Strategy: Understand the psychology behind these numbers in our pillar report: Fear vs. Logic: Why Waiting for a Market Crash is Costing You Equity.
Conclusion: Securing Your Future in Milton
Buying a home in 2026 as a first-time buyer in Milton with credit challenges isn’t easy—but it is possible. While others are discouraged by rising property taxes, savvy buyers recognize opportunities in inventory, negotiation, and income potential from legal basement suites.
Ready to find the "Hidden Gems" of Milton?
Click below to view Stale Listings (60+ days) or contact our team for a confidential assessment.
View Stale ListingsFAQs
1. Can I buy a house in Milton with a credit score under 600?
Yes. You may need alternative B-Lenders, a minimum 20% down payment, and higher short-term interest rates.
2. How much will the 2026 Milton property tax hike cost?
Roughly $250–$300 more per year on an $800,000 home.
3. Why is a legal basement important?
Rental income lowers your debt-to-income ratio, improving loan approval chances.
4. Biggest mistake with basement suites?
Ignoring parking bylaws—three off-street spaces are required.
5. Are there programs to help build suites?
Yes, the Canada Secondary Suite Loan Program allows refinancing up to 90%.